This case combines invented or transformed details for learning. It is not a real property or borrower file, valuation, lender assessment, approval, recommendation, or prediction.
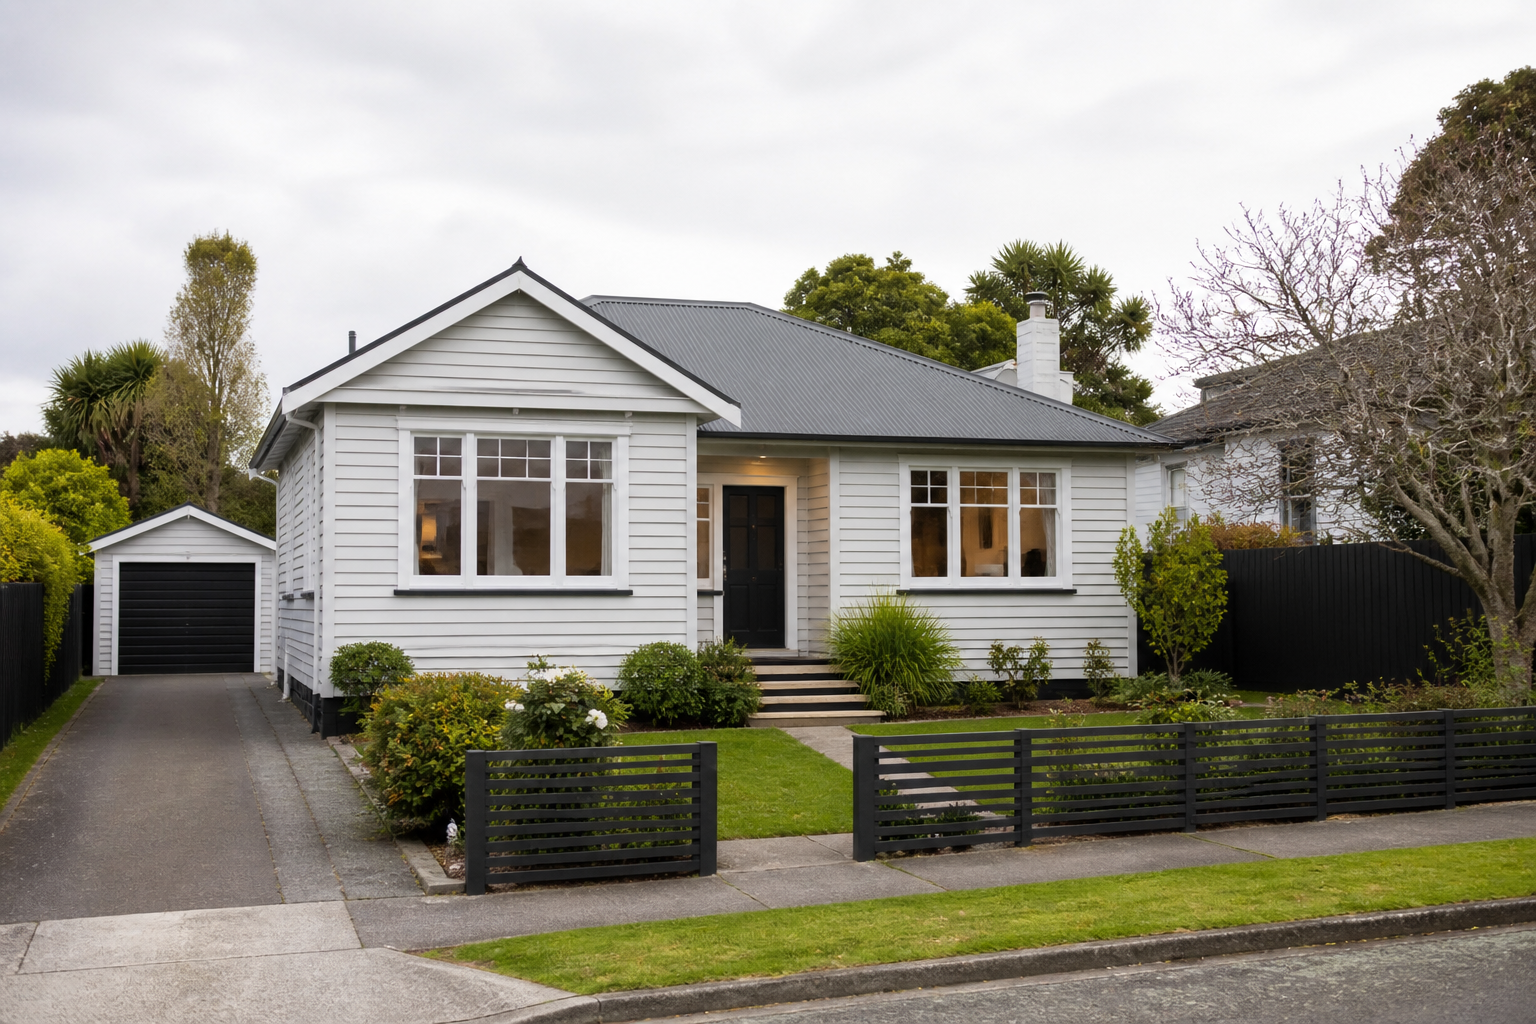
Download the full illustrative evidence pack (PDF) Newly authored hypothetical teaching document - not a real property report.
Independent document files
These files are separated so each evidence type can be reviewed on its own. They are fictional teaching documents, not official records.
Evidence path
- Property facts sheet
- Illustrative LIM summary
- Illustrative building inspection
- Illustrative valuation and insurance questions
Illustrative document pack
Fictional educational document
Property facts sheet
Synthetic property identity, approximate size, age band, value context, and evidence boundaries.
Fictional educational document
Illustrative LIM summary
No obvious example issue is assumed. The buyer still checks drainage, consents, notices, hazards, and discrepancies with the property and title.
Fictional educational document
Illustrative building inspection
Worn sealant, a loose handrail, older hot-water-cylinder insulation, and minor drainage observations are recorded with scope and access limitations.
Scope: visual, non-invasive inspection of accessible areas. Observations: handrail needs prompt safety attention; sealant and insulation are maintenance items; drainage observation should be checked during wet conditions. Limitations: no invasive opening-up, engineering opinion, code-compliance certification, or guarantee against concealed defects. Next steps: obtain a trade quote for the handrail, ask the lawyer whether any condition needs a written response, and keep a maintenance buffer.
Fictional educational document
Illustrative valuation and insurance questions
The value band is a teaching range, not a registered valuation. The buyer asks the insurer and lender what property-specific evidence they require.
These are hypothetical teaching documents. They are not copies of a real property file, LIM, building report, valuation, or insurance decision.
Related fictional borrower situations
These character situations use the same property evidence as a teaching bridge. They show how the question changes for a household; they do not predict a lender decision.
Clean first-home purchase
Mia Te Awa
Can a stable single-income buyer buy safely with a 20% deposit and retain a cash buffer?
Situation: Mia is a Hamilton medical administrator whose tidy savings habit is stronger than her small BNPL balance suggests.
Auction with competing bidders
Steve Walsh and Sam Patel
What is each household's hard bidding ceiling after legal, valuation, and buffer requirements?
Situation: Steve and Sam have excellent salaries but a thinner deposit than their target property suggests.
Auction with competing bidders
Jamie Wu and Pita Ngarimu
What is each household's hard bidding ceiling after legal, valuation, and buffer requirements?
Situation: Jamie and Pita are long-term flatmates testing whether a strong friendship can become a well-documented co-ownership arrangement.
Negotiation after inspection
Ella Morgan
How should inspection and consent risk change the offer and lending conditions?
Situation: Ella's income was never the problem; the story is whether her new savings behaviour becomes durable.
Questions this worked example raises
- What does the building report actually say was observed?
- Which items need a specialist or a quote before the condition deadline?
- Does the LIM raise any title, drainage, hazard, or consent question?
- Can the buyer obtain suitable insurance on workable terms?
- Does the valuation support the proposed lending and deposit?
How the evidence changes
The buyer compares the property facts with the listing and keeps a cash buffer instead of treating the maximum pre-approval as the budget.
The illustrative building report notes worn sealant, a loose handrail, older hot-water-cylinder insulation, and minor drainage observations. The buyer separates immediate safety work from ordinary maintenance.
The buyer's lawyer reviews the title, LIM, agreement conditions, insurance response, valuation questions, and the deadlines for each condition.
The buyer records planned maintenance and keeps evidence of work rather than assuming every improvement increases value dollar-for-dollar.
A normal property still needs a disciplined evidence check. A short list of minor defects is not the same as a clean bill of health, but it may be manageable if the buyer understands the cost, timing, and limitations.
This scenario is an illustrative teaching example. It is not a lending decision, recommendation, client story, or prediction of what any lender would do.